All articles
Lead Generation4 min read

Stop renting mortgage leads and start owning borrower demand

Shared lead lists put you in a five-way race you did not choose. Owned demand puts you in a conversation nobody else is having.

September 10, 2026 · UNPREC Intelligence desk · Reviewed for operators
Lead GenerationUNPREC / INTELLIGENCE

Shared leads are resold, so price competition starts before you speak.

September 10, 2026 · 4 min read

Operator’s takeaways

  • Shared leads are resold, so price competition starts before you speak.
  • Owned campaigns produce inquiries tied to your name and market.
  • Infrastructure you own keeps working after any single campaign ends.
Working definition

What this means in practice

Owned borrower demand is an inquiry generated through a campaign, page and follow-up system controlled by your business. Unlike a shared lead, the prospect enters through your positioning and the resulting first-party data remains attached to your pipeline.

Written for: Loan officers and mortgage brokers replacing shared leads with owned acquisitionRead our editorial and sourcing policy
Chapter 01

Rented demand has a built-in ceiling

When you buy a lead from an aggregator, the person on the other end filled in one form and expected one answer. Instead they get four or five calls in an afternoon, each one opening with a slightly different rate. The conversation becomes a price comparison before trust has any chance to form.

That model can still produce loans. What it cannot produce is a pipeline you control, because the supply, the price and the exclusivity are all decided by someone else.

Chapter 02

Owned demand behaves differently

An inquiry created by your own campaign arrives with context. The person saw your message, understood who you help, and chose to raise a hand. Your first call starts from interest rather than suspicion.

Owned demand also compounds. Creative that works keeps working, the audience data belongs to you, and every month of spend improves the next month of targeting instead of resetting to zero.

Chapter 03

What ownership actually requires

Ownership is not a single ad account. It is campaigns, an application flow, follow-up, tracking and a pipeline view that all speak to each other. Missing one piece and the rest leaks.

That is the whole argument for building the infrastructure once, properly, instead of stitching tools together every quarter.

Chapter 04

Choose a market before choosing a channel

A campaign cannot create useful demand when the audience is simply ‘anyone who needs a mortgage.’ Start with a real operating lane: first-time purchasers in one state, self-employed borrowers seeking non-QM options, investors buying two-to-four-unit property, or homeowners evaluating a refinance. The segment determines the questions, proof, media and follow-up.

Then write the offer around a decision the borrower is already trying to make. ‘See which purchase paths may fit your timeline’ is more useful than ‘Get a low rate.’ It attracts a question you can help answer without promising credit, pricing or approval.

Chapter 05

Build the owned-demand chain

The minimum system has six connected parts: an audience, a relevant message, a focused landing page, a short qualification flow, immediate contact and a pipeline that records every change. If source data disappears between the ad and CRM, you cannot know what to scale. If follow-up starts hours later, you waste attention you already paid to earn.

Use one borrower record from first click through funded outcome. Preserve campaign parameters, landing-page version, application answers, appointment status and final disposition. That history turns marketing from a monthly expense into an accumulating decision asset.

Chapter 06

Measure quality below the form

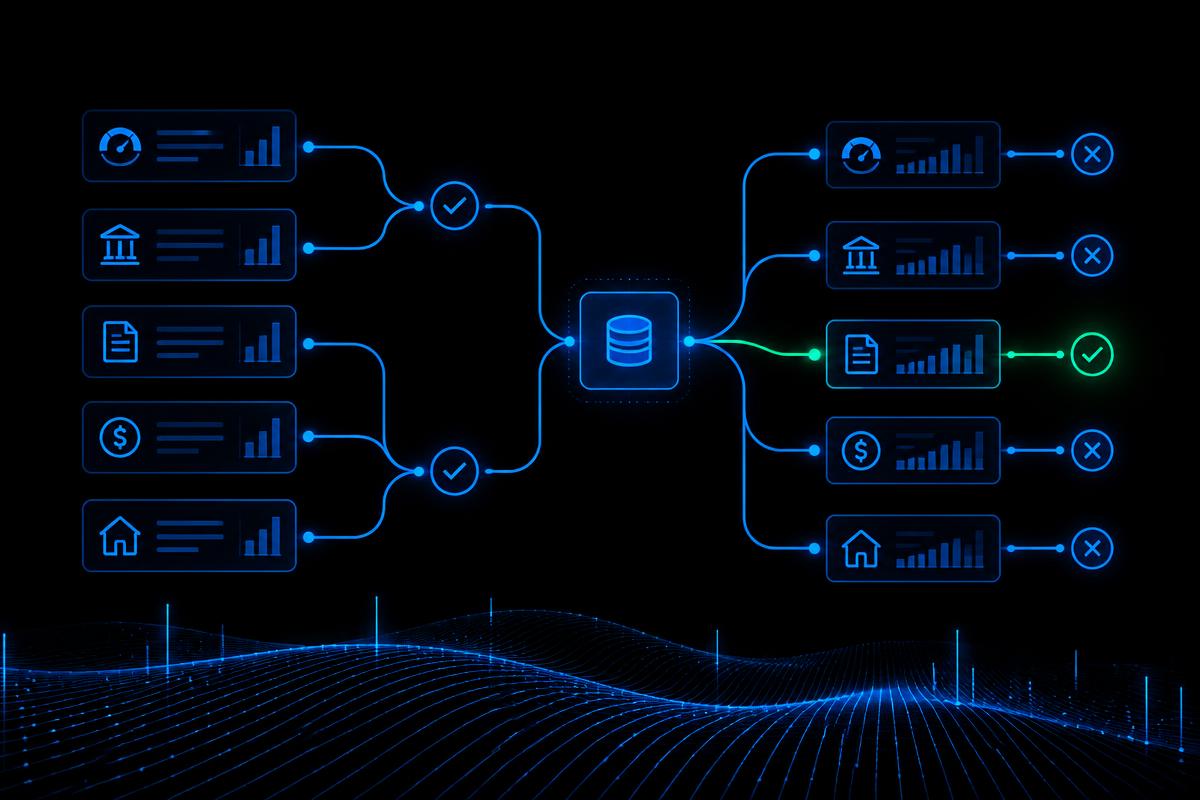
Cost per lead is a delivery metric, not a business result. Review qualified-application rate, contact rate, appointment rate, held-call rate, submitted-application rate and funded-loan rate by source. A higher-cost source can be the better investment when its borrowers answer, attend and proceed.

Use cohort reporting rather than judging every lead immediately. Mortgage cycles can be long, so compare groups acquired in the same period and allow enough time for progression. Keep an early view for operational decisions and a mature view for economics.
Chapter 07

A 30-day transition from shared to owned

Week one is definition: choose the segment, offer, qualifying fields and stage definitions. Week two is production: build the page, messages, tracking and pipeline. Week three is controlled launch with a small budget and daily lead-quality review. Week four is correction: remove friction, adjust routing and compare held appointments rather than celebrating form fills.

Do not switch every source off on day one. Treat existing lead vendors as a benchmark while the owned system collects enough volume. The objective is not ideological purity; it is a growing share of pipeline whose cost, message, data and follow-up you can control.

Implementation checklist

Put this into operation

  1. 01Choose one borrower segment and one local market
  2. 02Create one situation-led offer with a clear next step
  3. 03Capture source, campaign and consent on every inquiry
  4. 04Route qualified applicants into immediate follow-up
  5. 05Review cost per held call and funded loan by source weekly
Questions from the field

Frequently asked questions

Are exclusive mortgage leads the same as owned demand?

Not necessarily. An exclusive lead can still originate on another company’s property and leave you dependent on its pricing and policies. Owned demand begins with your campaign and borrower experience.

Which channel should a loan officer start with?

Start where your defined borrower segment can be reached consistently and where you can measure the full path to a held appointment. Channel fit matters less than message, follow-up and attribution working together.

How long before an owned campaign can be judged?

Judge delivery and contactability early, but assess loan economics by cohorts that have had enough time to progress. Set the evaluation window before launch so short-term noise does not control budget decisions.

Ready to build the pipeline instead of renting it?

Book a growth audit and we will map your current pipeline, then show exactly what the infrastructure would do for it.

Get Started

About 60 seconds · Private · No obligation

Explore the complete systemMortgage Lead Generation