Cost per lead hides the leak
A channel producing inquiries at a third of the price can still be your worst performer if almost none of them show up. Averages at the top of the funnel conceal what happens at the bottom.
Build the chain
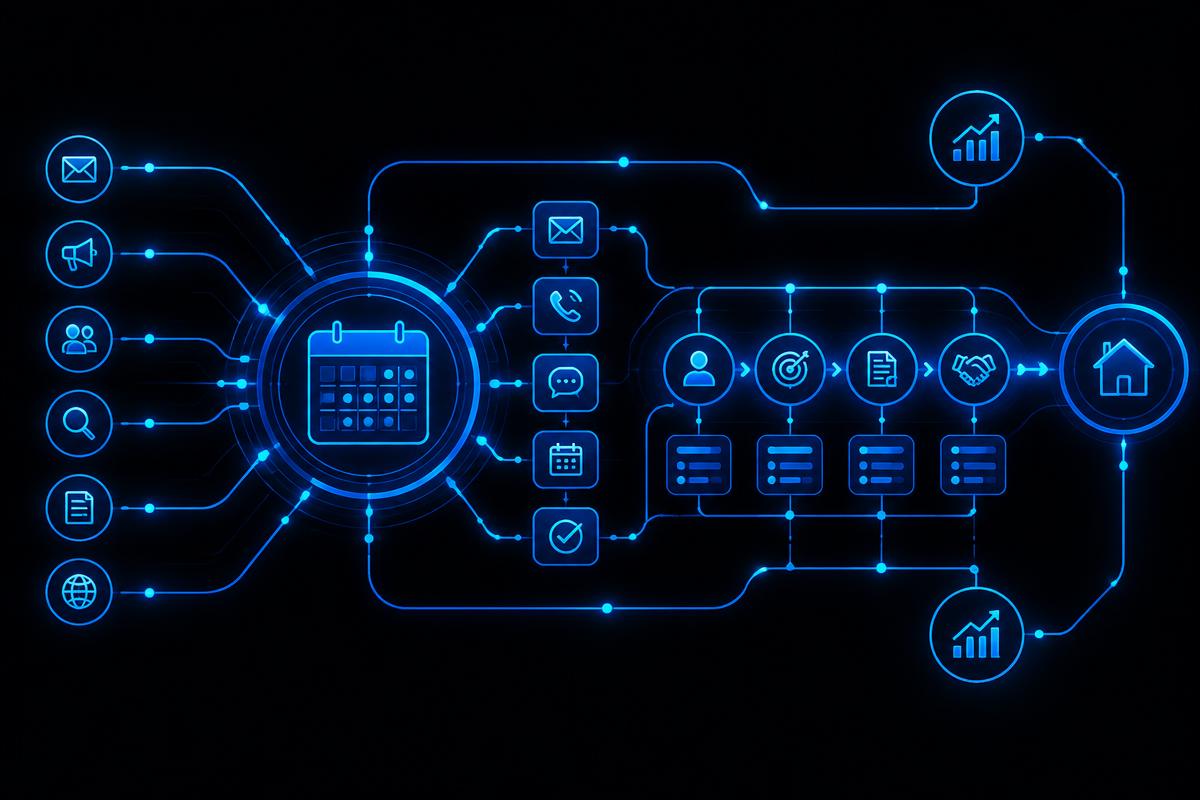
Applications, appointments set, consultations held, applications submitted, loans funded. Once every step has a rate, the constraint becomes obvious and arguments about channels get shorter.
Then move money deliberately
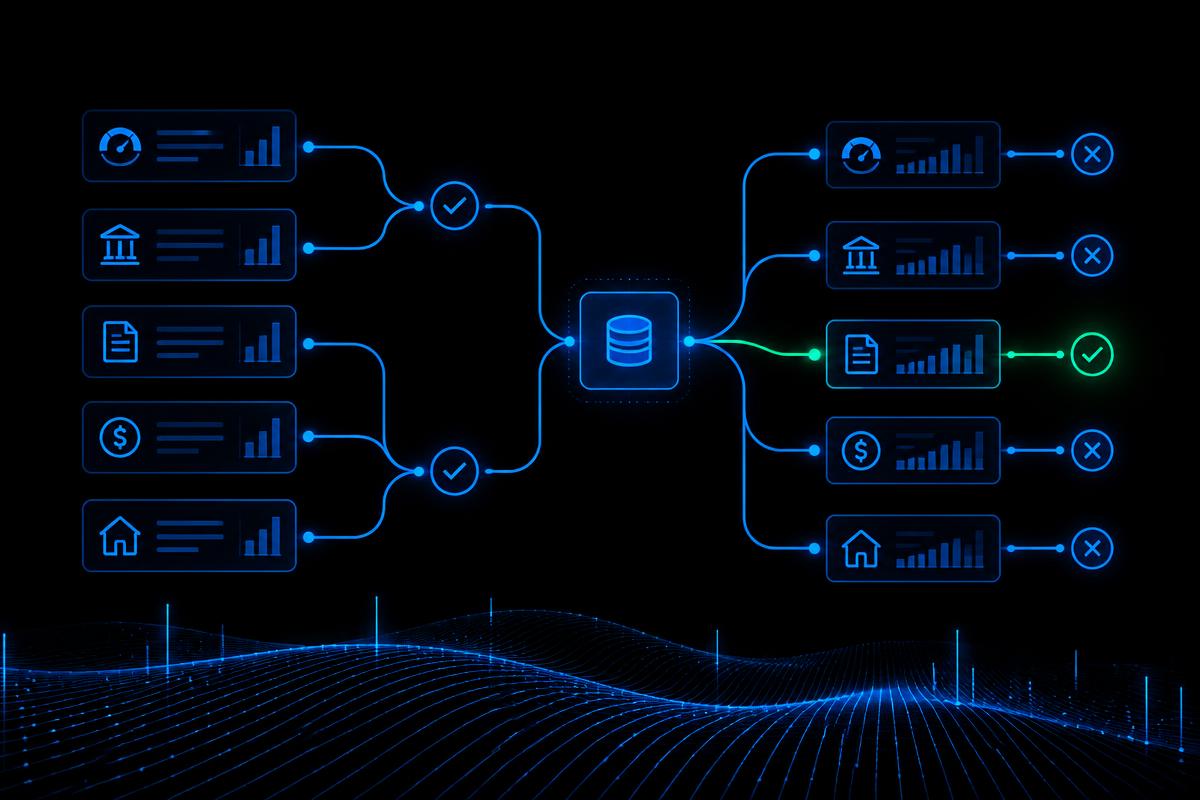
When you know cost per funded loan by source, budget decisions stop being opinions. You scale what closes and cut what merely fills a spreadsheet.
Use the complete acquisition equation
Start with total channel cost, including media and any directly assigned campaign cost. Divide by funded loans attributed to the same group of acquired leads. Then compare the result with gross revenue or contribution, not loan volume alone.
For example, if an illustrative cohort costs $12,000 and eventually produces six funded loans, acquisition cost is $2,000 per funded loan. That number is useful only if attribution is reliable and the cohort had time to mature.
Avoid the calendar-month trap
Dividing this month’s spend by this month’s fundings mixes different populations. Many funded loans originated from earlier marketing, while many current leads have not had time to progress. Use a lead-created cohort and update its outcome as records mature.
Keep a separate cash-flow dashboard for current-month spending and revenue. Operational cash flow and acquisition efficiency answer different questions.
Diagnose the conversion chain
Write the equation as cost per lead divided by each successive conversion rate: qualified, contacted, booked, held, submitted and funded. Small improvements lower acquisition cost multiplicatively. This shows whether the next dollar belongs in media, response coverage or appointment preparation.
Segment by source, campaign, product, geography and producer only when volume is sufficient. Tiny samples create dramatic percentages that do not repeat.
Set budget rules before emotions arrive
Define a target range, a warning range and a stop-review threshold based on economics your business can support. Include a minimum spend or lead count before making a decision. This keeps one good closing from making a weak source look brilliant.
Review quality comments alongside numbers. A channel can generate acceptable acquisition cost while creating operational strain, poor borrower experience or concentration risk.